Your will doesn’t control your super — and a binding death benefit nomination is the document that does. For couples heading into retirement, super is often the largest asset outside the home. Yet in June 2026, ASIC confirmed many families still wait six months or more for a death benefit.
Most people assume their will covers everything they own. However, superannuation sits outside your estate by default. Your super fund’s trustee decides who receives it, guided by superannuation law — not by your will. Consequently, this gap surprises almost every family we work with.
The good news is that the fix is simple, and it costs little or nothing. In most cases, it is a properly completed binding death benefit nomination lodged with your fund. The problem is that many people either never made one, or theirs has quietly lapsed. So this article walks through how the system works and where it fails. Then it shows how to close the gap calmly — long before it matters.
Why Your Super Sits Outside Your Will
Superannuation is held in trust for you by your fund. Because of this legal structure, it never automatically forms part of your estate. When you die, the trustee must pay your benefit under superannuation law. As a result, your will has no direct authority over it.
The law only allows the trustee to pay your super to certain people. These are your spouse, your children of any age, financial dependants, or someone in an interdependency relationship with you. Alternatively, the trustee can pay it to your legal personal representative — that is, your estate. Only then does your will apply.
In other words, there are two separate systems running side by side. Your will governs the house, the savings, and the share portfolio. Meanwhile, your super — often hundreds of thousands of dollars — follows its own rules entirely.
Your will only controls your super if the trustee pays the benefit to your estate first. Nothing guarantees that happens unless you have directed it in writing.
Who Receives Your Super — and the Tax They Pay
Here is where families get caught. Superannuation law and tax law use two different definitions of “dependant”. Your adult children can receive your super directly under superannuation law. However, unless they were financially dependent on you, tax law treats them differently.
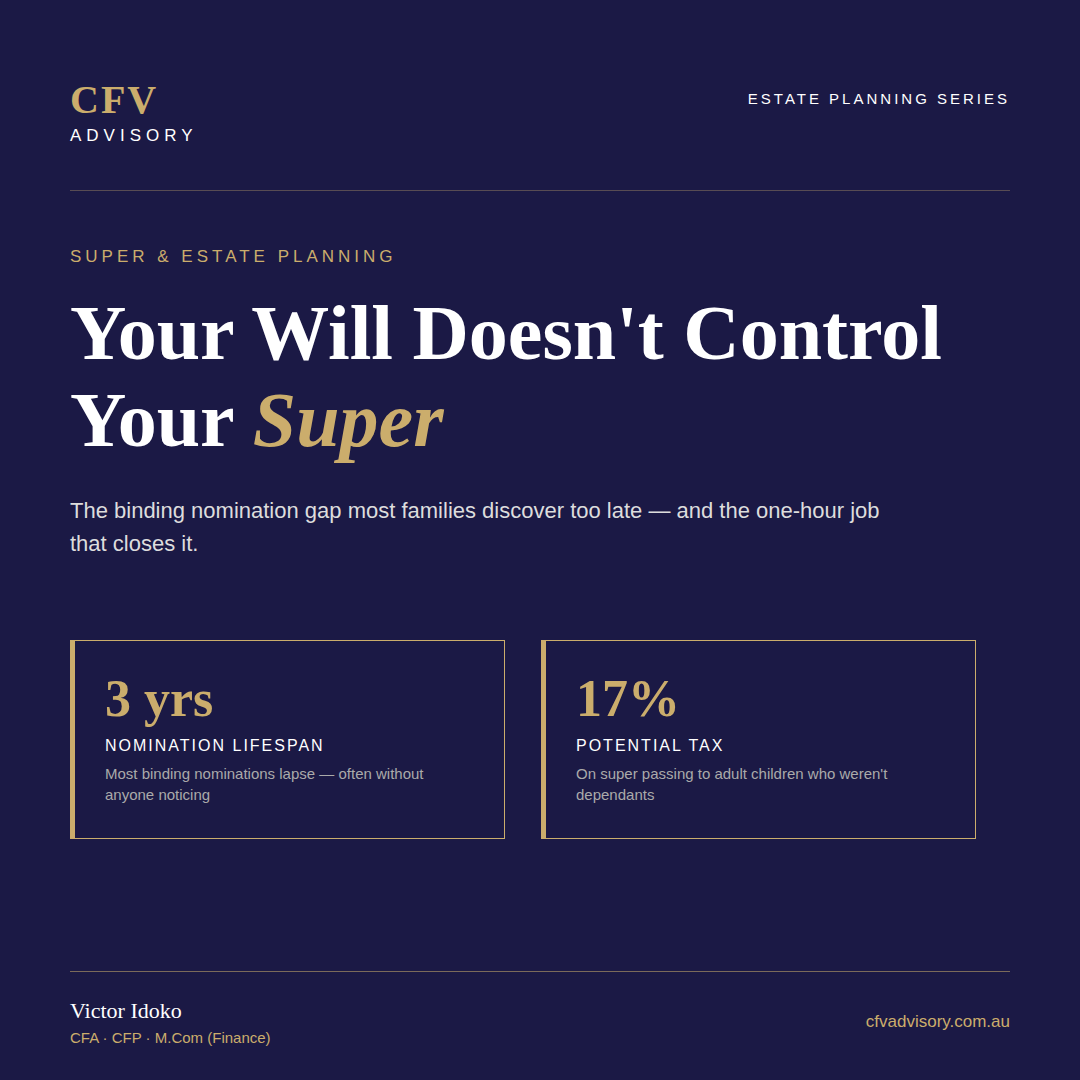
A spouse generally receives a lump sum death benefit tax-free. In contrast, an adult child can pay up to 17% tax on the taxable component of the same benefit. On a $600,000 balance that is largely taxable component, that can mean a bill approaching $100,000. Importantly, this is not a penalty — it is simply how the system is built.
There are legitimate strategies that can reduce this, particularly in the years just before and during retirement. For example, recontribution strategies can reshape the taxable component over time. That said, they involve caps, timing rules, and age conditions. For that reason, this deserves proper advice rather than guesswork.
Who receives your super changes how much tax is paid on it. The same dollars can arrive tax-free or with a five-figure tax bill attached.
What a Binding Death Benefit Nomination Actually Does
Most funds let you nominate beneficiaries in two ways. A non-binding nomination is guidance only — the trustee considers it, but can override it. A binding death benefit nomination, on the other hand, directs the trustee. If it is valid, the trustee must follow it.
That word “valid” carries a lot of weight. To be valid, a binding death benefit nomination must name eligible people and be signed correctly. It also needs two independent adult witnesses. Furthermore, most binding nominations lapse every three years unless your fund offers a non-lapsing version. A lapsed nomination is treated as if it barely exists.
For couples already drawing an account-based pension, there is a third option worth knowing. A reversionary nomination lets your pension continue automatically to your spouse, rather than stopping and being paid out. As a result, income keeps flowing during the hardest months, without a claims process. It also interacts with the transfer balance cap, so the choice between the two should be modelled, not assumed.
A valid, current binding death benefit nomination removes the trustee’s discretion. It turns “the fund will decide” into “you have already decided”.
Where Super Nominations Go Wrong
The failures we see follow a familiar pattern. First, the lapsed nomination — made a decade ago, expired quietly, never renewed. Second, the invalid one — witnessed by a family member, or naming someone the law doesn’t allow. A parent or sibling who wasn’t a dependant is a common example. Third, the outdated one — an ex-spouse still named, or a blended family arrangement the paperwork never caught up with.
When any of these happens, the decision returns to the trustee. Consequently, the fund must identify potential claimants, invite objections, and weigh competing claims. That process is slow at the best of times. For a grieving spouse relying on that money, it can be genuinely frightening.
In June 2026, ASIC released Report 831 on how super funds handle death benefit claims. Despite two years of regulatory pressure, claims resolved within six months improved by only 3% industry-wide. Several major trustees remain in court over delays. Put simply: the system is slow even when everything is in order. A valid nomination is the single best thing you can do to speed it up.
Every gap in your paperwork becomes a delay for your family. A binding death benefit nomination that lapsed in 2023 protects nobody in 2026.
Closing the Gap Before It Matters
None of this needs to be urgent, and none of it needs to be alarming. It simply needs to be done once, properly, and then reviewed. Here is the calm version of the checklist we walk clients through.
First, log into each super fund — both of you — and check what nomination is recorded. Next, confirm whether it is binding or non-binding, and when it lapses. Then, put the lapse date in your calendar as a recurring reminder. After that, sit your nominations beside your wills and make sure they tell the same story. Finally, if either of you has an account-based pension, ask whether a reversionary nomination suits your situation better.
For most couples, this review takes an hour and changes nothing except certainty. For some, it surfaces a real decision — about adult children, tax, blended families, or how the pension should continue. Those are exactly the conversations a solid retirement plan is built to settle. Moreover, they connect directly to the broader question of how your wealth passes on with purpose.
The Numbers Behind the Super Estate Planning Gap
A Quiet Job Worth Doing This Month
You have spent thirty years building this. The last step is making sure it lands where you intend, quickly and tax-efficiently. That is not a morbid exercise — it is simply the finishing work of a well-run financial life. And unlike markets or legislation, this one is entirely within your control.
Victor works through the retirement questions around this one on the Elevate Your Wealth podcast. The episode covers super drawdown, estate planning, and aged care.
Prefer to listen? Catch this article as an episode on the Two Incomes, One Plan podcast.
Victor helps Australian couples move into retirement with a clear, adjustable plan. That plan covers income, super, estate, and aged care before they become urgent. He is the author of 7 Basic Wealth Strategies and the new 5X Your Wealth. He also hosts the Elevate Your Wealth podcast. View More from CFV and Victor.
Explore Victor’s books, podcasts, and resources for couples planning a confident retirement.
This article contains general information only. It does not take into account your objectives, financial situation, or needs, and is not personal financial, legal, or tax advice. Superannuation, nomination, and tax rules change and depend on your circumstances. Before acting, consider whether the information is appropriate for you and seek advice from a licensed financial adviser. Victor Idoko is an authorised representative of a licensed Australian financial services provider.